What Financial Independence Means
You are financially independent when your investments can cover your living expenses without needing a paycheck. It does not mean you must stop working. It means working becomes a choice: you can change careers, work part-time, take a break or retire early.
The target is a single number, and it depends on two things: how much you spend and how much of your portfolio you can safely withdraw each year.
👉 Calculate your own FI number with our free financial independence calculator →
The 4% Rule and the 25x Rule
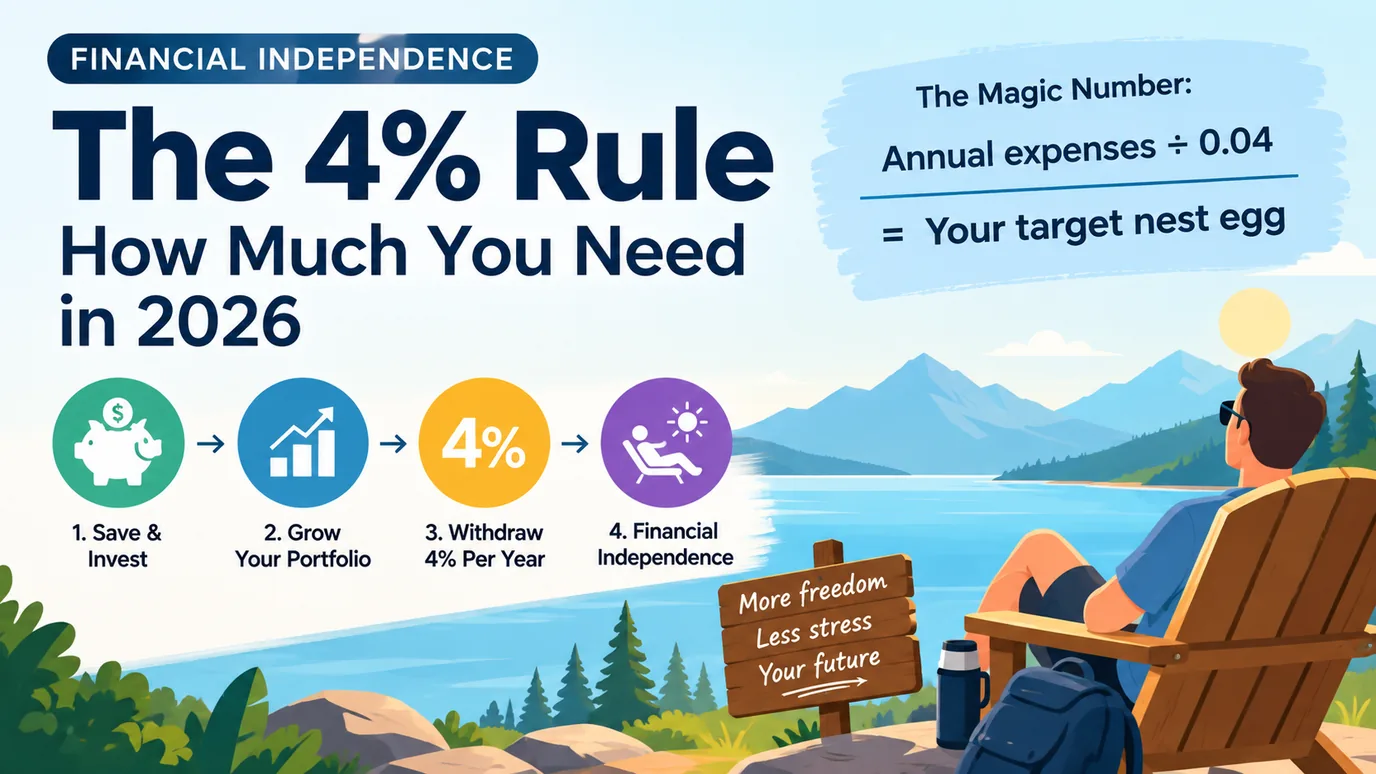
The 4% rule says that if you withdraw about 4% of your portfolio in the first year of retirement and then adjust that dollar amount for inflation each year, your money has historically lasted through a 30-year retirement in most cases. The idea comes from research in the 1990s, including a well-known study of historical U.S. market returns.
Turn it around and you have the 25x rule, because 1 ÷ 0.04 = 25:
FI number = yearly spending ÷ withdrawal rate = yearly spending × 25
| Yearly Spending | FI Number at a 4% Withdrawal Rate | Monthly Spending |
|---|---|---|
| $40,000 | $1,000,000 | $3,333 |
| $60,000 | $1,500,000 | $5,000 |
| $80,000 | $2,000,000 | $6,667 |
| $100,000 | $2,500,000 | $8,333 |
Swipe sideways to see all columns. Every $1,000 you cut from yearly spending lowers your FI number by $25,000, and every $1,000 you spend is $25,000 you must save. That is why spending is the most powerful lever of all.
The Withdrawal Rate Changes the Answer
The 4% figure is a benchmark, not a guarantee. A longer retirement, such as one starting at 40 or 45, is exposed to more years of market ups and downs, so many early retirees use a lower rate. For $60,000 a year of spending:
| Withdrawal Rate | FI Number | Years to Reach It (Baseline Savings) |
|---|---|---|
| 3% | $2,000,000 | 26 years |
| 3.5% | $1,714,286 | 24 years |
| 4% | $1,500,000 | 22 years |
| 5% | $1,200,000 | 20 years |
Going from 4% to 3.5% adds $214,286 to the target and about two years to the timeline. A higher rate such as 5% shortens the wait but raises the chance of running out. Choose a rate you are comfortable with, and consider more flexibility, such as cutting spending in bad market years.
The years above come from this baseline: $80,000 already invested, $24,000 saved a year, a 7% assumed yearly return, and spending of $60,000.
Savings Matters as Much as Spending
With the same $80,000 start and a 4% rule, here is how long it takes at different savings amounts:
| Yearly Savings | Years to Reach $1.5 Million |
|---|---|
| $12,000 | 28 years |
| $24,000 | 22 years |
| $36,000 | 19 years |
| $48,000 | 16 years |
Doubling savings from $24,000 to $48,000 cuts about six years off the timeline. Because the two levers work together, spending less raises savings and lowers the target at the same time.
In the baseline you have saved about 5.3% of the target so far ($80,000 of $1.5 million), and the gap is $1,420,000. To get there in 10 years you would need to save about $7,737 a month; in 20 years, about $2,259 a month.
Counting Social Security, Pensions and Rental Income
Your portfolio does not have to cover everything. Income that arrives regardless of the portfolio reduces what it must supply. If Social Security will provide $24,000 a year in retirement, the portfolio only needs to cover the remaining $36,000:
| Other Income in Retirement | Portfolio Must Cover | FI Number | Years to Reach |
|---|---|---|---|
| None | $60,000 a year | $1,500,000 | 22 years |
| Social Security $24,000 a year | $36,000 a year | $900,000 | 16 years |
| Social Security $24,000 + pension $12,000 | $24,000 a year | $600,000 | 12 years |
That is a powerful effect, but be careful: Social Security usually starts between 62 and 70, so someone who retires at 45 has to bridge the gap with the portfolio. See our guide on when to claim Social Security to estimate the benefit, and remember that fewer than 35 years of earnings lowers it.
What the 4% Rule Does Not Cover
- Taxes. Withdrawals from traditional retirement accounts are taxed as income. Plan the number before or after tax consistently.
- Healthcare before Medicare. If you retire before 65, you pay for health insurance yourself, which can be a large cost.
- Early withdrawal penalties. Money in retirement accounts usually carries a 10% penalty before age 59½, with exceptions; many early retirees plan a mix of taxable and retirement accounts.
- Market order. Poor returns in the first years of retirement hurt much more than the same returns later, known as sequence-of-returns risk.
- Inflation and changes in spending. The rule adjusts withdrawals for inflation, but real life includes one-time costs.
- Long retirements. The original research tested 30-year periods.
Five Steps to Your FI Number
- Estimate your yearly spending in retirement. Start with what you spend today and remove costs that will end, such as a mortgage or commuting, then add healthcare.
- Pick a withdrawal rate you can live with, such as 3.5% to 4%.
- Multiply: yearly spending ÷ withdrawal rate.
- Subtract other income, such as Social Security, before you divide.
- Check the timeline with your own savings, and test how a lower expense level or a bigger deposit shortens it.
To see how your money can grow along the way, use the ETF and index fund calculator and read our guide on index fund investing.
Frequently Asked Questions
What is the 4% rule?
It is a guideline that you can withdraw 4% of your portfolio in the first year of retirement, then adjust for inflation each year, and expect your money to last about 30 years based on historical U.S. data.
How do I calculate my financial independence number?
Multiply your expected yearly spending by 25, or divide it by your chosen withdrawal rate. If other income will cover part of your spending, subtract it first.
Is the 4% rule still safe?
It is a reasonable starting point for 30-year retirements, but it is not a guarantee, and future returns may differ from the past. Early retirees often use 3% to 3.5%, or stay flexible with spending.
How much do I need to retire at 50?
It depends on spending: $60,000 a year needs about $1.5 million at 4%. Retiring at 50 also means paying for healthcare before 65 and waiting for Social Security, so many plan a more conservative withdrawal rate.
Does the calculator include taxes?
No. It works with your pre-tax spending needs and a withdrawal rate. Taxes on withdrawals depend on your account types and income.
Conclusion & Recommended Next Steps
Your FI number is simple to compute and powerful to know: it turns a vague goal into a target you can measure. Start with your yearly spending, divide by your withdrawal rate, and check how long it takes at your savings rate. Then test what a lower expense level or a higher savings amount does to the timeline.
Financial Independence Calculator
Find your FI number and the years to reach it.
FIRE Retirement Calculator
Compare Lean, Regular, Fat, Barista and Coast FIRE.
Social Security Calculator
Estimate the benefit that can reduce your FI number.
401(k) & Roth IRA Calculator
See how retirement accounts can build your number.
Disclaimer: This guide is intended solely for educational and informational purposes and does not constitute personalized financial, investment, legal, or tax advice. The 4% rule is a historical guideline, not a guarantee, and the figures above are illustrations based on the stated assumptions. Consult a qualified financial professional before you plan your retirement.